Transfer Pricing at Arm’s Length. Value Aligned, Globally Delivered.

Transfer Pricing at Arm’s Length. Value Aligned, Globally Delivered.

Transfer Pricing at Arm’s Length. Value Aligned, Globally Delivered.

From planning to defense, NexusPrice powers cross-border pricing strategies

From planning to defense, NexusPrice powers cross-border pricing strategies

Who are we?

Who are we?

Who are we?

At NexusPrice, we help Global businesses turn Transfer Pricing from a compliance task into a strategic advantage. In a world of growing Regulation and Complexity, we make sure your pricing aligns with your goals, manages risk and drives value across borders.

We combine deep expertise with smart tools to deliver accurate, future-ready solutions. For us, Transfer Pricing is not just about rules, it's about clarity, alignment, and long-term success.

At NexusPrice, we help Global businesses turn Transfer Pricing from a compliance task into a strategic advantage. In a world of growing Regulation and Complexity, we make sure your pricing aligns with your goals, manages risk and drives value across borders.

We combine deep expertise with smart tools to deliver accurate, future-ready solutions. For us, Transfer Pricing is not just about rules, it's about clarity, alignment, and long-term success.

At NexusPrice, we help Global businesses turn Transfer Pricing from a compliance task into a strategic advantage. In a world of growing Regulation and Complexity, we make sure your pricing aligns with your goals, manages risk and drives value across borders.

We combine deep expertise with smart tools to deliver accurate, future-ready solutions. For us, Transfer Pricing is not just about rules, it's about clarity, alignment, and long-term success.

What Sets us Apart

What Sets us Apart

What Sets us Apart

Delivered to 15+ Listed Companies

Served 40+ Multinational Corporations (MNCs)

Completed 300+ Transfer Pricing Projects and 100+ Advisory

5+ Global TP Databases Accessed

Successfully defended & saved over $2B in Disputed Tax Litigations

Regulatory Expertise covering 20+ Jurisdictions worldwide

Transfer Pricing Solutions delivered across 20+ countries

Sector Expertise across 15+ Industries

Leveraging a global network across 50+ countries

Our Global Footprint, Quantified.

Our Global Footprint, Quantified.

Our Global Footprint, Quantified.

0+

Years in business

Years in business

0+

Projects Delivered

Projects Delivered

0+

Jurisdictional Expertise

Jurisdictional Expertise

$0B+

Intercompany Transactions Reviewed

Intercompany Transactions Reviewed

0+

Fortune 500 Companies Advised

Fortune 500 Companies Advised

What We Do Best?

What We Do Best?

What We Do Best?

Whether you’re expanding into a new market, preparing for an audit, or redesigning your global pricing strategy, we're here to support you at every step.

Whether you’re expanding into a new market, preparing for an audit, or redesigning your global pricing strategy, we're here to support you at every step.

Countries.

Countries.

Countries.

Global Coverage. Local Expertise.

We deliver end-to-end Transfer Pricing solutions across regions — from Asia-Pacific and North America to Europe, the Middle East, and Africa.

Whether it’s designing TP models, benchmarking, or preparing global documentation, our team combines deep knowledge of local tax laws with a unified, globally consistent approach.

Global Coverage. Local Expertise.

We deliver end-to-end Transfer Pricing solutions across regions — from Asia-Pacific and North America to Europe, the Middle East, and Africa.

Whether it’s designing TP models, benchmarking, or preparing global documentation, our team combines deep knowledge of local tax laws with a unified, globally consistent approach.

Why choose us?

Why choose us?

Why choose us?

At NexusPrice, we’re upfront about pricing, deliverables, and timelines, building trust from day one. Our TP solutions align with Indian and global regulations, covering everything from planning and documentation to benchmarking, CbC reporting, and tax authority representation.

At NexusPrice, we’re upfront about pricing, deliverables, and timelines, building trust from day one. Our TP solutions align with Indian and global regulations, covering everything from planning and documentation to benchmarking, CbC reporting, and tax authority representation.

  • Transparent and flexible engagement

    Transparent and flexible engagement

  • Global standards with local execution

    Global standards with local execution

  • Full-spectrum TP services under one roof

    Full-spectrum TP services under one roof

  • GTPIQ powers smart, automated TP decisions

    GTPIQ powers smart, automated TP decisions

How We Work.

How We Work.

How We Work.

We understand your business, craft the right plan, execute it seamlessly, and stay with you every step, no fluff, just results.

We understand your business, craft the right plan, execute it seamlessly, and stay with you every step, no fluff, just results.

  • Client-Centric Onboarding

    Client-Centric Onboarding

    We begin with an in-depth understanding of your business model, intercompany transactions, and transfer pricing challenges.

    We begin with an in-depth understanding of your business model, intercompany transactions, and transfer pricing challenges.

  • Scope Definition & Transparent Pricing

    Scope Definition & Transparent Pricing

    We clearly define the scope, timelines, and deliverables—offering transparent, upfront pricing with no hidden costs.

    We clearly define the scope, timelines, and deliverables—offering transparent, upfront pricing with no hidden costs.

  • Jurisdiction-Specific Approach

    Jurisdiction-Specific Approach

    Our team strategizes and prepares documentation based on the relevant local regulations and global standards (OECD, BEPS).

    Our team strategizes and prepares documentation based on the relevant local regulations and global standards (OECD, BEPS).

  • Data-Driven Benchmarking & Analysis

    Data-Driven Benchmarking & Analysis

    We conduct robust economic analysis using global databases and industry-specific comparables to determine arm’s length pricing.

    We conduct robust economic analysis using global databases and industry-specific comparables to determine arm’s length pricing.

  • Review & Risk Assessment

    Review & Risk Assessment

    We conduct TP health checks, identify potential risks, and suggest mitigations before regulatory scrutiny arises.

    We conduct TP health checks, identify potential risks, and suggest mitigations before regulatory scrutiny arises.

  • Proactive Communication

    Proactive Communication

    Regular updates, clear milestones, and a dedicated team to ensure transparency and smooth execution throughout the project.

    Regular updates, clear milestones, and a dedicated team to ensure transparency and smooth execution throughout the project.

Our Valuable Insights

Our Valuable Insights

Our Valuable Insights

Latest Blog

Related Party Transactions Under Company Law: Aligning Arm’s Length Pricing with Corporate Governance

Indian companies frequently enter into transactions with group entities, promoters, directors and other related parties. These arrangements may be examined under multiple regulatory frameworks, including the transfer pricing provisions of income tax law and the corporate governance requirements of the Companies Act, 2013.

Although both frameworks refer to the arm’s length principle, their scope, objectives and approval requirements are not identical. A company that relies on a transfer pricing study as its only compliance measure may overlook separate governance obligations.

Section 188 and the Arm’s Length Exemption

Section 188 of the Companies Act, 2013 regulates specified related party transactions, including transactions relating to the sale or purchase of goods, property, leasing, services and other prescribed arrangements.

Such transactions may require approval of the Board of Directors and, where applicable, shareholders, subject to the prescribed thresholds and conditions. Transactions entered into in the ordinary course of business and on an arm’s length basis are generally exempt from certain approval requirements under this provision.

The arm’s length assessment therefore has an important governance function. It helps establish whether the transaction qualifies for the relevant exemption, in addition to supporting the commercial basis of the arrangement.

Audit Committee and Listed Company Requirements

Where applicable, the audit committee must approve related party transactions in accordance with the Companies Act. Omnibus approvals may be available for repetitive transactions, subject to prescribed conditions and the committee’s approval framework.

Listed companies are also subject to the related party transaction requirements under the SEBI Listing Obligations and Disclosure Requirements Regulations. These include additional requirements relating to approvals, materiality and disclosures.

The applicable thresholds and procedures may change through regulatory amendments. Companies should therefore review the current provisions before each approval and reporting cycle.

Why Corporate Governance and Tax Tests May Differ

The transfer pricing provisions primarily examine whether specified transactions between associated enterprises satisfy the arm’s length principle. Company law has a wider governance purpose and may cover domestic related party dealings that do not fall within the scope of international transaction provisions.

The methodologies and documentation used for tax benchmarking are not automatically prescribed as the basis for every company law assessment. Accordingly, a transaction supported by a transfer pricing study may still require separate consideration of its commercial rationale, approval process and governance implications.

This distinction is particularly relevant for domestic transactions involving promoter-group entities and other related parties.

Using Transfer Pricing Analysis in Approval Processes

A well-prepared benchmarking study can provide useful evidence to the Board or audit committee when considering the terms of a related party transaction.

The approval note should identify the relevant transaction, refer to the benchmarking analysis where available and explain the basis for concluding that the terms are appropriate. The date and financial information underlying the study should also be considered, particularly where the transaction is recurring.

Where the pricing or scope of services has changed from the previous year, the reasons should be documented rather than relying automatically on an earlier approval or study.

Consistency in Disclosures and Audit Records

Related party information appears across multiple corporate and tax records, including the register of contracts, Board and committee approvals, financial statement disclosures and the accountant’s report under the Income-tax Act.

Differences in the identification of related parties, transaction descriptions or reported values can lead to audit queries and compliance concerns. Maintaining a consolidated schedule of related parties and transactions can help ensure consistency across these records.

Conclusion

Related party compliance requires more than demonstrating that a transaction is priced at arm’s length. Companies should align their transfer pricing analysis with the applicable approval and disclosure requirements under company law, maintain a consolidated transaction record and ensure that Board approvals, financial statements and tax filings present a consistent account of their related party dealings.


Read More

Latest Case Law

Norway Gulating CoA: CUP Adjustment on Intra-Group Gas Sales Set Aside for Insufficiently Comparable Agreements

TotalEnergies EP Norge AS (“the taxpayer”), a Total Group subsidiary producing oil and gas on the Norwegian continental shelf and taxed at a combined 78%, sold dry gas on a short-term basis to its UK sister company, TotalEnergies Gas & Power Ltd. (TGP). For 2014 to 2017 there were about 1,800 transactions under a 2002 framework agreement, worth roughly NOK 7.8 billion. The Oil Tax Office held that the pricing ignored the flexibility and preferential access TGP enjoyed and, applying CUP, added EUR 0.55 per MWh, increasing income by NOK 217 million.

Assessee’s Contentions

Revenue’s Contentions

Court’s Judgement

The taxpayer contended that the sales involved standardised products priced against hub reference prices (index or closing prices), and were therefore equivalent to sales to independent parties.

The Oil Tax Office held that the pricing did not reflect the value of the flexibility and preferential access enjoyed by TGP, for which independent parties would have paid a separate premium.

The Court assessed the roughly 1,800 transactions collectively: TGP in practice obtained stable access to the taxpayer’s short-term volumes and security of supply. Documentation gaps weighed against the taxpayer, and a reduction of income was proven.

It submitted that no flexibility was transferred to TGP and that TGP’s realistically available alternatives had to be considered under a two-sided CUP analysis.

Applying CUP, it benchmarked the sales against independent volume-flexible agreements and fixed a flexibility value of EUR 0.55 per MWh, raising income subject to special petroleum tax by NOK 217 million.

However, the volume-flexible medium-term agreements used as comparables priced a different type of benefit and risk than fixed-volume intra-group deliveries, so the discretionary assessment rested on an incorrect application of the law.

The Court of Appeal dismissed the State’s appeal and set aside the Oil Tax Office’s decision, though for reasons other than the taxpayer’s main argument. A reduction of income was found, but the comparables used priced a different type of benefit and risk.


Read More

Latest Update

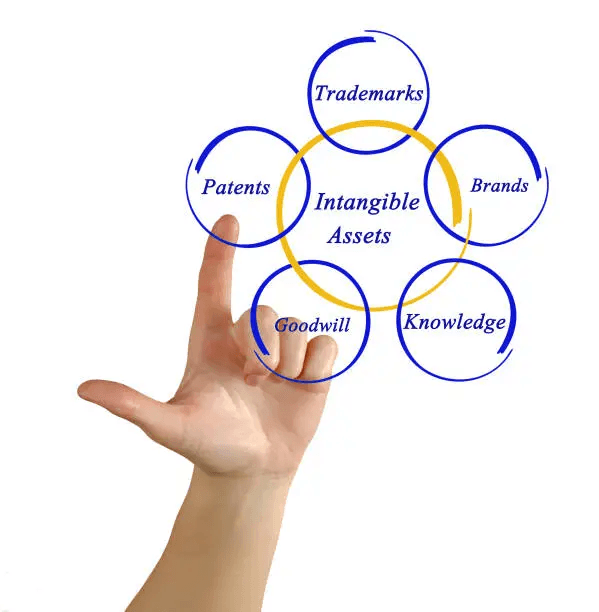
Intangible Asset Management in Multinationals

Importance of Intangible Assets in Multinationals

Intangibles are the principal driver of value creation and a major source of sustainable competitive advantage for most multinationals; technological transformation and the digital revolution have accelerated this phenomenon, allowing intangibles to play a key role in profit generation. 

Conversely, their intangible nature has significant challenges regarding valuation and location, which can generate considerable tax risks. 

Challenges in Appraising Intangibles

Appraising an intangible asset is complex due to its unique nature and lack of direct comparables, which require specialized methods and detailed analysis. Inaccurate appraisal can lead to discrepancies with tax authorities and Transfer Pricing adjustments, affecting the company’s tax burden. 

Management of Intangible Assets and Related Risks

The location of an intangible asset within the corporate structure is a strategic decision with potentially significant tax implications. Since intangibles generate considerable income, tax authorities may question the allocation of this income and the related costs, particularly if they consider the structure was designed to benefit from tax havens. The allocation of intangibles must reflect the economic substance and DEMPE (Development, Enhancement, Maintenance, Protection, and Exploitation) functions within the corporate group to avoid Transfer Pricing adjustments and tax disputes. 

Evolution of the International Regulatory Environment

In recent years, international bodies, such as the OECD, have intensified their efforts against tax base erosion and profit shifting, which resulted in implementing measures, such as the BEPS Action Plan, which intends to ensure the taxation of profits where real economic activities take place and value is created. 

Recommendations for Multinational Enterprises

In order to mitigate the tax risks related to intangible assets, multinational companies should have: 

  • Comprehensive documentation: Maintain detailed records supporting ownership, appraisal, and location of intangible assets. 

  • Periodic reviews: Regularly evaluate Transfer Pricing policies and ensure alignment with current market practices and regulations. 

  • Application of the DEMPE approach: Address the tax effects of intangibles by focusing on the Development, Enhancement, Maintenance, Protection, and Exploitation (DEMPE) functions. 

  • Expert advice: Have international tax experts who can guide you on best practices and regulatory amendments. 

Conclusion

Intangible assets are critical to value creation and sustainable competitive advantage in multinationals. Conversely, their unique nature and the absence of direct comparables in the marketplace hinder their proper valuation. This complexity can lead to disputes with tax authorities and Transfer Pricing adjustments, affecting the company’s tax burden. Therefore, they should support their cost and expense allocations with solid documentation to substantiate the allocation criteria used. These measures will help ensure compliance with tax regulations and reduce risks associated with intangible asset management. 

Read More

We’re just a message away from starting something great together.

We’re just a message away from starting something great together.

We’re just a message away from starting something great together.

Frequently Asked

Questions

Frequently Asked

Questions

Frequently Asked

Questions

What is transfer pricing and why is it important?

What industries does NexusPrice support for transfer pricing services?

Can NexusPrice assist us during the transfer pricing audit?

What is GTPIQ and how does it support my business?

How does NexusPrice ensure its benchmarking analysis is compliant?

What are Advance Pricing Agreements (APAs)?

Ready to Elevate Your Brand?

Ready to Elevate Your Brand?

Ready to Elevate Your Brand?

Let’s team up and turn your vision into results.

Let’s team up and turn your vision into results.

Let’s team up and turn your vision into results.

Transfer Pricing at Arm’s Length. Value Aligned, Globally Delivered.

  • Contact

  • +91 93609 91001

  • info@nexusprice.org

  • Willingdon Crescent, 4th Floor,#6/2, Dr. S.S.Badrinath Road, Nungambakkam, Chennai 600 006

©2025 NexusPrice. All rights reserved

©2025 NexusPrice. All rights reserved